China's Rare Earth Deadline: What November 2026 Means for IT
A diplomatic pause is not a solution — it is a deadline. On November 10, 2026, Beijing will decide whether to activate sweeping rare earth export controls that were suspended just over a year ago. For datacenter operators, server manufacturers, and anyone building AI infrastructure, that date is now arguably the most consequential supply-chain event on the calendar.
What Is Happening
In October 2025, China introduced a second wave of rare earth export controls that would have required export licences for any product containing more than 0.1 percent rare earth elements — a threshold that captures servers, networking switches, fibre optic components, and AI accelerator hardware. On November 7, 2025, Beijing suspended that wave for one year, setting a review date of November 10, 2026, according to the Foundation for Defense of Democracies' contemporaneous analysis and the European Parliament Think Tank's documentation of the Chinese government announcement. That suspension bought time, but it did not resolve the underlying chokehold.
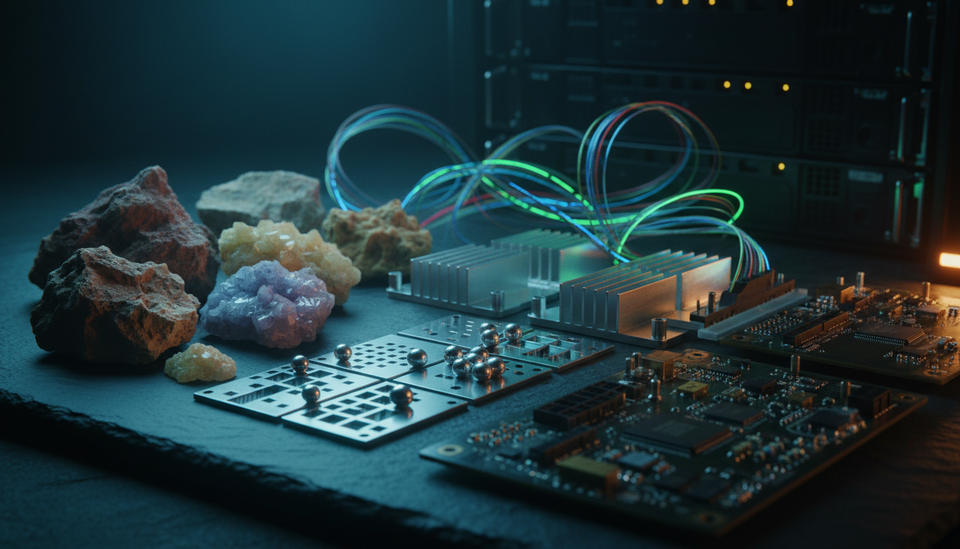
The specific materials at the centre of datacenter concern are yttrium and erbium — elements that receive far less press coverage than the magnet metals (neodymium, dysprosium) but are equally critical to IT infrastructure. Yttrium is used in phosphors for displays, in yttrium-iron-garnet (YIG) filters in networking equipment, and in stabilised zirconia for thermal barrier coatings in high-performance servers. Erbium is the backbone of erbium-doped fibre amplifiers (EDFAs) — the technology that makes long-haul and datacenter fibre optic interconnects function.
IEEE Spectrum flagged yttrium curbs as the underreported threat to datacenter build-outs, noting that China remains the dominant — and in many cases near-exclusive — source for both elements. The damage is already measurable: shipments of yttrium are down approximately 75 percent year-to-date in 2026, according to reporting from The Register and LavX News citing IEEE data.
China's Refining Dominance and the Licensing Lever
China's market position makes this leverage real. The International Energy Agency (IEA) documented that China controlled roughly 90 percent of global rare earth refining capacity as recently as 2023. New projects in the United States and Malaysia have nudged that figure down to approximately 85 percent as of 2025, and the IEA projects it could fall to 70 percent by 2035 — but that timeline offers no relief before November 10, 2026.
It is worth noting that even the "paused" controls retain significant levers. The Foundation for Defense of Democracies (FDD) noted in its November 2025 analysis that Beijing's Ministry of Commerce (MOFCOM) preserved discretionary licensing authority, meaning approvals can be delayed or denied on a case-by-case basis without formally activating the broader controls. In practical terms, the chokehold is already partially engaged.
Why This Matters for Datacenters
The IEA has put a dollar figure on the exposure: China's rare earth export curbs endanger an estimated $6.5 trillion in downstream Western industrial production, with the US and Europe accounting for a significant share of that figure, according to Nikkei Asia's July 2026 reporting on the IEA assessment. Datacenters sit inside that number alongside automotive, defence, and energy sectors.
The 0.1 percent rare earth threshold in the suspended October 2025 controls is not a high bar — virtually every piece of enterprise IT hardware crosses it. If those controls activate in November without modification, operators importing servers, switches, or optical transceivers from manufacturers using Chinese-processed rare earths would face a licensing gauntlet that could delay shipments by months or halt them entirely.
The rare earth supply chain will remain exposed to geopolitical disruption until the United States and its allies build fully integrated, mine-to-magnet supply chains outside of China — and building such capacity will take years, not months. — CSIS, 2026
The timing compounds the pressure. Hyperscalers and colocation providers are in the middle of the largest datacenter construction wave in history, driven by AI workload demand. Supply chain disruptions that delay hardware delivery by even one quarter can cascade into missed capacity commitments, broken SLAs, and deferred revenue. As discussed above, China's refining share has only moved from 90 percent to 85 percent in two years — structural diversification is simply too slow to offer a buffer before the November decision.
What You Should Do
For Datacenter Operators and IT Procurement Teams
- Audit your bill of materials now. Work with hardware vendors to identify which components contain yttrium, erbium, or other heavy lanthanides. Any component with Chinese-processed rare earth content above 0.1 percent is potentially subject to the suspended controls if they activate.
- Map your vendor's supply chain, not just your vendor. Your server OEM may be US-headquartered, but their optical transceiver supplier or filter component manufacturer may source processed rare earths directly from China. Demand supply chain transparency documentation — vendors without clear answers represent elevated procurement risk.
- Build strategic inventory buffers where feasible. With yttrium shipments already down 75 percent, spot availability is tightening regardless of what happens in November. Evaluate whether 90-to-180-day buffer stock for high-risk components (optical transceivers, YIG-based networking filters, server thermal components) is achievable and cost-justified.
- Prioritise alternative-sourced components. Some vendors are already qualifying components using rare earths processed outside China (US, Malaysia, Australia). Prioritise these in new procurement cycles even if they carry a cost premium today — reducing dependency before the November deadline is the objective.
- Watch the November 10 date actively. Assign someone to monitor MOFCOM announcements. Beijing's decision — extend the suspension, activate the controls, or introduce a modified framework — will require rapid procurement response.
- Engage your hardware vendors on contingency plans. Ask your top-tier server and networking vendors what their November scenario planning looks like. Vendors without a clear answer are a risk signal.
For Security and Risk Teams
- Incorporate rare earth supply chain risk into formal assessments. This is no longer a theoretical geopolitical scenario — it is an active, time-bounded threat with a known decision date. Treat November 10 as a trigger event requiring pre-positioned response plans.
- Brief executive leadership and boards before October. The $6.5 trillion global exposure figure and a specific date warrant C-suite awareness and scenario planning, not just procurement-level tracking.
The Bigger Picture
China's rare earth export controls are not a trade dispute tactic in isolation — they are part of a deliberate, multi-year strategy to leverage resource dominance as geopolitical influence. Modern Diplomacy's August 21, 2026 analysis asked directly whether Beijing is preparing to let the rare earth truce with Washington expire, noting that the November review coincides with a period of unresolved US-China trade tensions.
The IEA's public financing data offers a structural counterpoint: global commitments to new critical mineral projects grew substantially between 2023 and 2025, but investment in the sector actually fell 9 percent in 2025 as price volatility and geopolitical uncertainty chilled private capital, per The National's July 2026 reporting on IEA data. The gap between the urgency of diversification and the pace of actual investment is the core vulnerability.
Finally, we should be direct about the practical implication. Until mine-to-magnet supply chains exist outside China at meaningful scale, every datacenter build plan carries an embedded geopolitical dependency that no firewall or redundancy architecture can patch. The November 10 review is not the end of that dependency — but it is the date on which its consequences may become acute.
Sources
- IEEE Spectrum — Rare Earth Shortage
- The Register — Datacenters Face Direct Hit from China Rare Earth Curbs
- LavX News — Datacenters Face Direct Hit from China's Rare Earth Curbs
- Modern Diplomacy — Is China Preparing to Let Its Rare Earth Truce Expire?
- European Parliament Think Tank — China's Rare Earth Export Restrictions
- FDD — China Pauses Some Rare Earth Export Curbs While Retaining Levers of Control
- IEA — Export Controls on Critical Minerals
- Nikkei Asia — China's Rare Earth Curbs Endanger $6.5tn of Western Industry
- The National — China's Rare Earth Export Curbs May Hit $6.5tn in Global Production
- CSIS — Rare Earth Export Restrictions One Year Later
- Rare Earth Mining — China Rare Earth Export Controls
- AI in Asia — China Rare Earth Grip on Asia AI Hardware
- Noah News — China's Rare Earth Export Controls Near a Pivotal Renewal